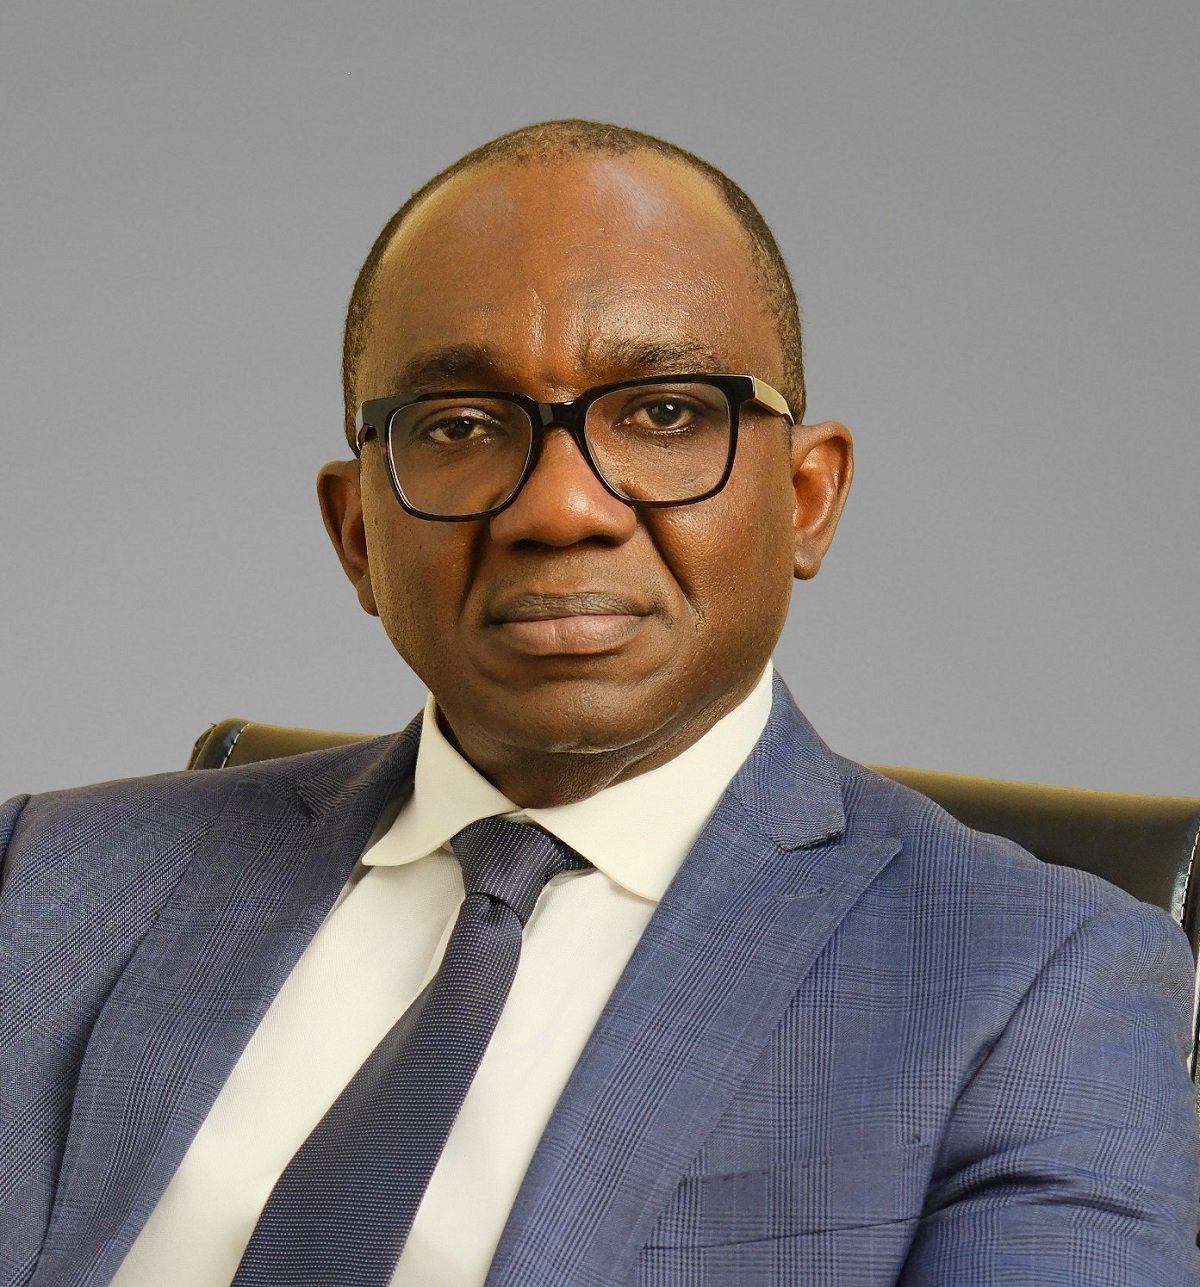
Mathesis Analytics CEO has urged Nigerian Lenders to end blanket interest rates.
NewsOnline Nigeria reports that the Founder and Chief Executive Officer of Mathesis Analytics Inc., Winston Osuchukwu, has called on Nigerian financial institutions to replace blanket interest rates with data-driven pricing models that reflect the specific risk profile of each borrower.
Osuchukwu said the traditional lending system, which places different borrowers within broad risk categories and offers them similar interest rates, often penalises financially responsible customers and excludes viable businesses from accessing credit.
He made the argument in an opinion article titled “Pricing Risk in the Dark: The End of Blanket Interest Rates in Retail Lending.”
ALSO: $14.86m Fraud: EFCC Tells Timipre Sylva to Present Himself for Questioning
Using the example of two small businesses applying for a ₦5 million term loan, Osuchukwu explained that companies with similar revenues and operating histories could have significantly different financial behaviours.
While one business might depend heavily on extended supplier credit to finance its working-capital cycle, another could maintain steady cash flows and sell inventory more quickly.
According to him, conventional credit scorecards could approve both businesses for the same SME loan and offer them identical interest rates despite their different risk profiles.
“The issue is not that lenders cannot identify risk. It is that traditional lending architecture groups materially different borrowers into broad risk segments,” he said.
“When reliable information is scarce, this is understandable. But when lenders have access to richer information about how customers actually behave financially, treating materially different risks the same is inefficient.”
Osuchukwu argued that the next stage of lending should move beyond making a simple decision on whether to approve or reject a loan.
He said lenders should use predictive information to determine how much to lend, the appropriate loan duration and the interest rate that reflects each borrower’s financial behaviour.
Blanket Pricing Penalises Lower-Risk Borrowers
The Mathesis Analytics CEO said blanket pricing assumes that borrowers within the same segment are sufficiently similar to justify receiving identical interest rates.
In practice, he explained, lenders using this approach price the average customer rather than the individual borrower.
This creates what he described as an “invisible micro-subsidy,” where lower-risk borrowers are charged more to compensate for the anticipated defaults of customers with higher risk profiles.
At the same time, businesses that narrowly fall outside rigid credit thresholds may be denied loans despite being commercially viable.
“The result is an inefficient system where good borrowers overpay and viable borrowers are excluded,” Osuchukwu said.
Behavioural Data Can Improve Risk Assessment
Osuchukwu identified improved risk visibility as the key to creating fairer and more efficient retail lending.
He said Nigeria’s financial ecosystem generates extensive behavioural information through bank transactions, merchant activity, mobile money usage, utility payments and supplier settlements.
When properly analysed, he said, this information can help lenders assess default risk more accurately instead of relying mainly on broad revenue figures and static historical records.
According to him, tracking daily cash flows can expose hidden volatility and provide a clearer picture of the operational health of a business.
He added that continuously updated data could alert lenders when a borrower’s transaction activity declines or cash inflows improve, allowing risk assessments to reflect current financial realities.
Lenders Can Adopt Personalised Interest Rates
Osuchukwu said better risk visibility would allow financial institutions to move from fixed pricing categories to more flexible models.
Under such a system, algorithms could analyse a borrower’s combined financial footprint, including internal account history and external indicators such as payment patterns, to estimate the borrower’s risk more precisely.
That assessment could then be translated into a personalised interest rate.
While lenders would retain their cost-of-funds baseline and risk limits, Osuchukwu said the price of each loan could be adjusted to match the borrower’s actual level of risk.
He explained that this approach would allow lenders to offer lower rates to prime customers while extending appropriately priced credit to borrowers with higher but manageable risks.
Precision Pricing Could Expand Financial Inclusion
The Mathesis Analytics founder said personalised loan pricing could improve profitability for lenders and create a more rational credit market for consumers and SMEs.
He noted that borrowers with strong transactional records could use their financial behaviour as a bankable asset capable of reducing their cost of credit.
“Clean transactional records become bankable assets that actively lower the cost of credit, freeing resilient borrowers from subsidising the defaults of their peers,” he said.
Osuchukwu added that better analytical models could help lenders distinguish between businesses without conventional credit histories and those that pose genuine repayment risks.
This distinction, he said, could expand productive credit to underserved individuals and businesses while supporting the commercial objectives of financial institutions.
“By mathematically distinguishing between businesses that lack a conventional credit history and those that are genuinely risky, the system naturally extends productive credit to underserved segments—turning financial inclusion into a byproduct of profitable market efficiency,” he stated.
Osuchukwu predicted that increased competition would eventually force lenders to abandon static rate cards because of the value lost through inefficient pricing.
He said financial institutions that successfully use multi-source data and algorithmic models to price individual risks would be better positioned to lead the next phase of banking.
For consumers and SMEs that have been restricted to rigid loan products or excluded from formal credit, he said the transition would mark the emergence of financing that more accurately reflects their financial circumstances.