By Ndefo Precious
As digital payments reshape how Nigerians work, trade and manage money, OPay is leveraging technology, local partnerships and customer service to expand access to financial services and strengthen consumer confidence.
For a commercial driver, a market trader or a small business owner, access to financial services is more than a convenience. It means receiving payment for a trip, collecting money for goods sold or sending funds home without wasting valuable time. When these transactions are fast, reliable, secure and easy to complete, people can focus more on earning a living.
This is the opportunity digital finance presents. For OPay, which has operated in Nigeria since 2018, it is also an opportunity to build trust by making financial services more accessible and useful to everyday Nigerians.
Nigeria has made considerable progress in expanding access to financial services, although significant gaps remain. According to the 2026 Access to Financial Services survey by Enhancing Financial Innovation and Access (EFInA), 79 per cent of Nigerian adults, representing approximately 94.2 million people, use at least one financial product or service. Formal financial inclusion reached 73 per cent, equivalent to about 87.2 million adults, surpassing the 70 per cent target established under the National Financial Inclusion Strategy.
ALSO: Design Week Lagos 2026: Stakeholders Seek Funding, Better Education to Grow Africa’s Creative Industry
The survey also indicated that digital financial services reached 64.4 per cent of adults, up from 45 per cent in 2023 and 34 per cent in 2020. However, approximately 21 per cent of adults remained financially excluded, with rural communities continuing to face greater barriers than urban areas. These figures highlight both the progress made and the work still required to ensure that financial services reach people wherever they live and work.
OPay’s approach centres on mobile technology, digital payments and an extensive merchant network. The objective is to make everyday financial transactions more convenient for individuals and businesses that increasingly depend on digital channels to receive and transfer money.
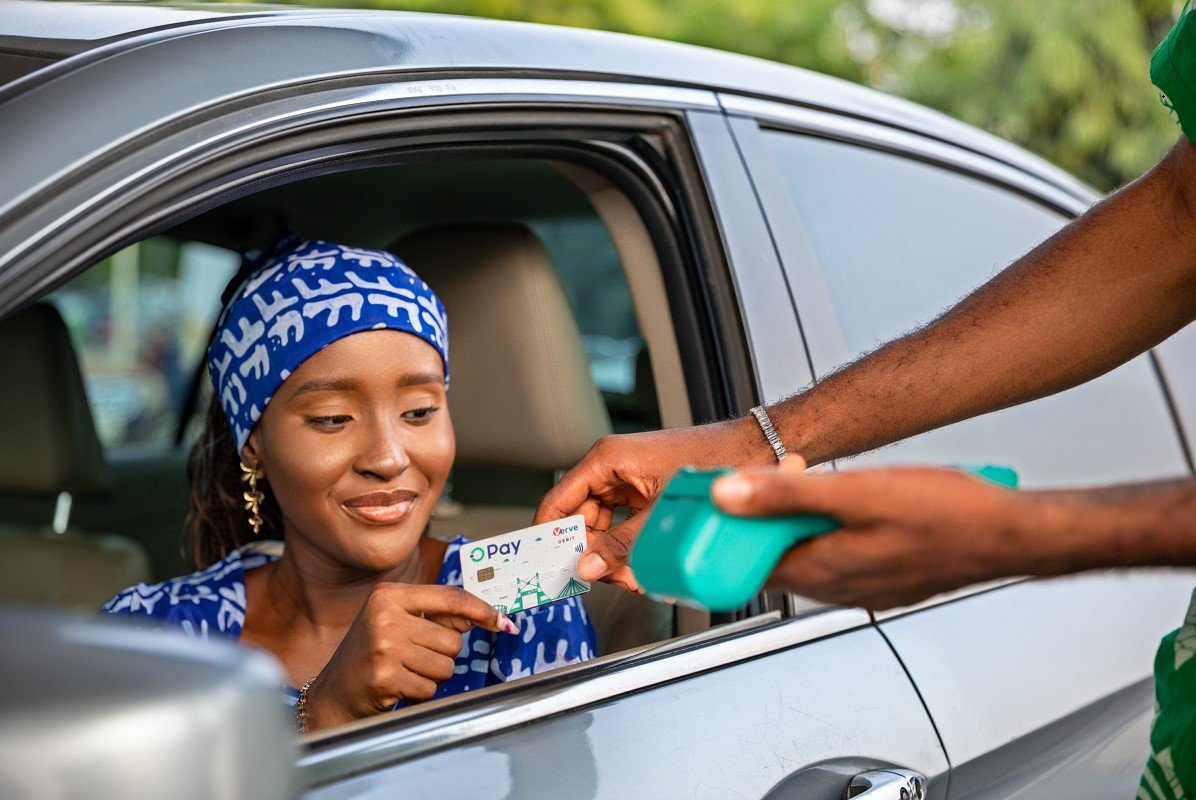
For commercial drivers and ride-hailing operators, for instance, digital payments can simplify the process of collecting fares and managing earnings. The widespread use of OPay among drivers of local cabs and ride-hailing services illustrates how mobile financial services can become part of everyday economic activity. The value extends beyond convenience. When people can receive payments and transfer money with less dependence on cash, they have more flexibility in managing their income and meeting their financial obligations.
Small businesses are another important part of Nigeria’s digital finance ecosystem. OPay reported that more than one million merchants and businesses were on its network as of June 2026. This network provides a channel through which participating businesses can receive digital payments and serve customers who prefer cashless transactions.
For a neighbourhood shop, food vendor or service provider, accepting digital payments offers customers an additional way to pay. It can also reduce some of the practical challenges associated with handling cash, including the need to maintain change and make deposits. Merchants who provide eligible financial services may also earn commissions, creating an additional income stream.
These relationships demonstrate how digital financial services can support economic activity beyond the immediate transaction. By helping merchants receive payments and access financial-service opportunities, fintech platforms can contribute to the development of local commerce.
The impact also extends to employment. Operating a digital financial services business requires professionals in technology, compliance, customer support, sales and operations. Its wider network can create additional earning opportunities for merchants and agents who participate in providing financial services. In this sense, financial technology can support livelihoods both within a company and across the businesses and communities that use its services.
Access to digital finance alone, however, does not guarantee customer confidence. Trust is also shaped by how financial institutions respond when transactions fail, complaints arise or customers need assistance. A failed transfer can disrupt a business’s daily operations, while an unresolved complaint can leave a customer uncertain about the safety of their money. In such situations, responsive customer service becomes an essential part of the financial service itself.
Clear communication, timely updates, practical assistance and easily accessible official support channels can help customers understand what has happened and what steps they should take next. For fintech companies, effective complaint resolution is particularly important because customers often depend on digital platforms for routine transactions, including receiving income, paying suppliers and supporting family members.
OPay has identified reliability and security as central to its technology infrastructure. Its public filings reportedly indicate that more than 99 per cent of transactions initiated on its app were completed successfully on the first attempt during the first half of 2026. While transaction performance is an important measure of reliability, sustained trust also depends on how providers protect customer information, communicate with users and address problems when they occur.
As digital financial services become more deeply integrated into everyday life, providers must continue to demonstrate that their platforms are not only convenient but also dependable and responsive to customer needs.
The expansion of digital payments is taking place alongside continuing efforts to improve access to cash across Nigeria. In March 2026, the Central Bank of Nigeria introduced a requirement for card issuers to deploy at least one automated teller machine (ATM) for every 7,500 payment cards issued. Implementation is being phased, with full compliance scheduled for 2028. The policy is intended to improve access to cash and strengthen ATM service availability.
Cash remains important to many Nigerians, particularly in communities where digital infrastructure, connectivity or access to suitable devices may be limited. Improving cash availability therefore remains relevant to the broader objective of financial inclusion. At the same time, the growth of mobile banking, instant transfers and merchant-based payment services demonstrates that consumers are increasingly accessing financial services through channels beyond traditional banking infrastructure.
The policy challenge is to ensure that improvements in cash access complement, rather than overlook, the changing ways Nigerians manage their money. A broader approach to financial inclusion would consider the different needs of urban and rural communities, the availability of digital infrastructure, the role of merchants and agents, and the importance of providing customers with reliable options for both cash and electronic payments.
For fintech companies such as OPay, this creates an opportunity to continue investing in digital services while responding to the realities of the communities they serve.
Despite progress in digital financial services, important gaps remain in access to credit, insurance and other products that help households manage financial shocks. EFInA’s findings indicate that rural communities continue to experience lower levels of financial inclusion than urban areas, highlighting the need for targeted efforts to reach underserved populations.
Regulatory requirements relating to customer identification, fraud prevention and agent banking are also important to maintaining confidence in the financial system. However, these requirements must be implemented in ways that protect consumers while allowing legitimate providers to extend services to communities that remain underserved. Clear rules, proportionate compliance requirements and regular engagement between regulators and financial-service providers can help strike this balance.
The Central Bank of Nigeria has also emphasised the importance of innovation in expanding access to financial services. At the launch of Payments System Vision 2028, CBN Governor Olayemi Cardoso highlighted the target of achieving 95 per cent financial inclusion by 2028 and stressed that “the goal is inclusion, not exclusion.” Achieving this ambition will require collaboration among regulators, banks, fintech companies, merchants and consumers.
Technology can make financial services easier to access, but its impact depends on the strength of the infrastructure supporting it, the effectiveness of consumer protection measures and the ability of providers to respond to the needs of different communities.
For OPay, the opportunity lies in translating its local operations into practical benefits for individuals and businesses. These include reliable transactions, accessible customer support, stronger merchant relationships and broader access to digital financial services.
The importance of these efforts is best understood through the everyday experiences of customers. A driver receiving payment for a trip, a shop owner collecting money from a customer or a family member sending funds home illustrates how digital finance can support routine economic activity.
However, lasting confidence cannot be built through technology alone. It requires consistent service delivery, responsible operations, effective complaint resolution and a commitment to protecting customers. For regulators, the task is to maintain safeguards that protect the financial system while providing room for responsible innovation. For consumers, awareness of security practices and the use of official channels remain important to safer digital transactions.
Ultimately, trust is built through everyday results. When a digital payment works as expected, when a merchant can serve a customer without unnecessary delays, and when a user receives timely assistance with a problem, financial technology becomes more than an application on a phone. It becomes a practical tool for work, opportunity and financial inclusion.